UAE VAT Deregistration Update 2026: 30-Business-Day Deadline for Companies Closing or Liquidating
FTA Regulatory & Service Update • Last Reviewed: 28 September 2026
Executive Summary: Key VAT Deregistration Timelines
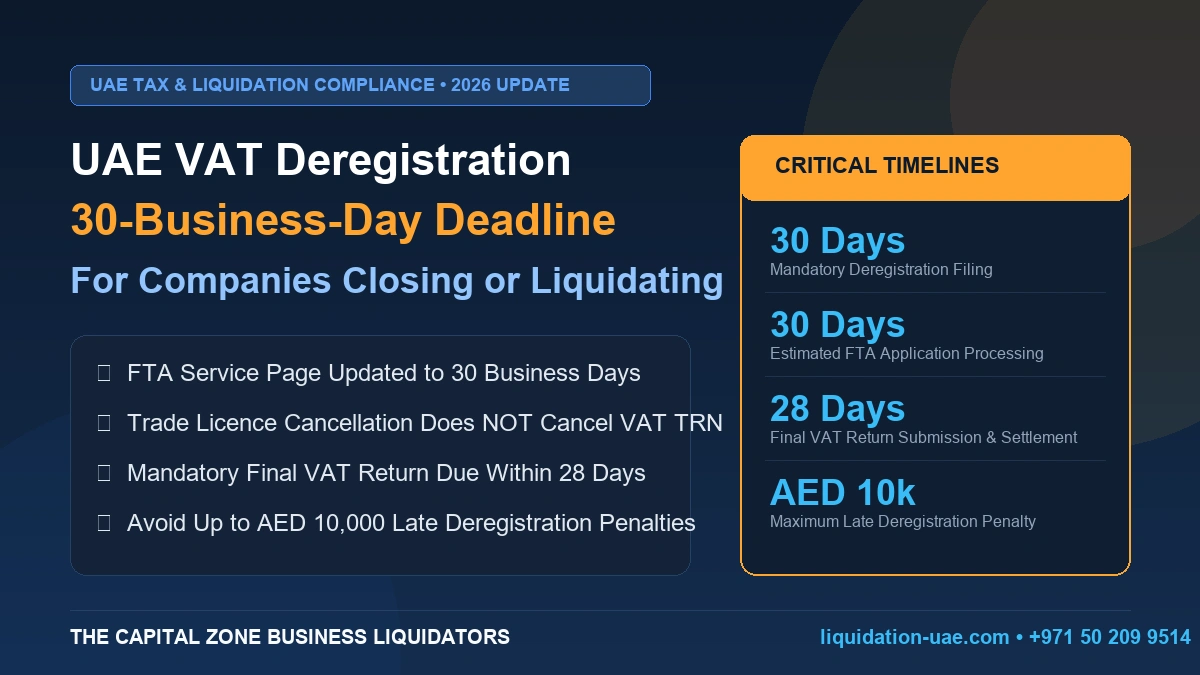
- Mandatory Application Window: The Federal Tax Authority’s (FTA) live service page now communicates a 30-business-day application deadline from the date the deregistration obligation arose (distinguished from the 20-business-day timeline in published Executive Regulations).
- Trade Licence Disconnect: Cancelling your commercial licence or entering liquidation does NOT automatically cancel your VAT TRN.
- Final Return Obligation: The final VAT return and any tax payable must be settled within 28 days from the effective deregistration date.
- Late Filing Penalties: Late deregistration attracts an initial fine of AED 1,000, plus AED 1,000 per month (up to a maximum of AED 10,000).
Businesses closing or liquidating in the UAE need to deal with more than their trade licence. If the company is registered for Value Added Tax, its VAT registration with the Federal Tax Authority (FTA) does not automatically disappear when the business stops trading, enters liquidation or cancels its licence.
A significant update appeared on the Federal Tax Authority’s VAT Deregistration service page on 24 September 2026. The FTA’s current online guidance now states that, where VAT deregistration is mandatory, the application must be submitted within 30 business days from the date the deregistration obligation arose. The same page now gives an estimated FTA processing time of 30 business days from receipt of a completed application.
For companies already planning company liquidation in the UAE, this makes VAT deregistration an important part of the closure timetable rather than something to address after every other company-cancellation step has finished.
There is, however, an important technical point businesses should understand: the currently published VAT Executive Regulation still contains a 20-business-day deregistration period. We explain that difference below and why companies should still act as early as possible.
Quick Answer: What Is the UAE VAT Deregistration Deadline in 2026?
The FTA’s current VAT Deregistration service page, updated 24 September 2026, states 30 business days for a mandatory VAT deregistration application from the date the deregistration obligation arises.
It also states:
| VAT Deregistration Requirement | Current FTA Service Information |
|---|---|
| Mandatory deregistration application | Within 30 business days |
| FTA processing time for a complete application | 30 business days |
| Further processing after additional information is submitted | Up to another 30 business days |
| Final VAT return and payment | Within 28 days from the effective deregistration date |
| FTA service fee | Free |
For a company being liquidated, the practical message is simple: do not assume cancelling the trade licence also cancels the VAT registration.
What Changed in the UAE VAT Deregistration Guidance?
The September update is particularly notable because the FTA’s VAT Deregistration service page had recently shown a shorter period.
An earlier version of the same page, updated on 10 September 2026, stated that mandatory deregistration applications were due within 20 business days, with an estimated 20-business-day processing period.
The page updated on 24 September 2026 now shows 30 business days for both the mandatory application window and normal processing of a completed application.
Current FTA Website vs Published VAT Executive Regulation
Businesses and advisers should also be aware that Article 14 of the currently published VAT Executive Regulation states that a registrant must apply for deregistration within 20 business days after a mandatory deregistration event occurs.
This creates an important difference between:
- The FTA’s current live service guidance: 30 business days; and
- The published VAT Executive Regulation: 20 business days.
The September 2026 amendments to the VAT Executive Regulation under Cabinet Decision No. 149 of 2026 dealt with other VAT matters, including input tax recovery, composite supplies, the Capital Asset Scheme and related provisions; they did not identify Article 14’s deregistration period among the provisions amended.
What Should a Closing Company Do?
A business should not use the website update as a reason to postpone deregistration unnecessarily.
Where possible, a company entering liquidation should begin reviewing and preparing its VAT deregistration application as soon as the relevant deregistration condition occurs.
Until the published legal material and current FTA service guidance are fully aligned, filing promptly—rather than waiting until the end of the longer period—is the safer compliance approach.
When Is VAT Deregistration Mandatory in the UAE?
VAT deregistration is not required simply because a shareholder has decided to close a company. The tax position depends on whether a statutory deregistration condition has occurred.
Under the UAE VAT law, mandatory VAT deregistration applies in situations including:
1. The Business Stops Making Taxable Supplies
This is the most relevant situation for many companies undergoing liquidation. Once the company permanently stops carrying on taxable business activities and does not expect to resume relevant supplies, VAT deregistration becomes mandatory.
2. Taxable Supplies Fall Below the Voluntary Registration Threshold
Mandatory deregistration can also arise where taxable supplies over the relevant 12-month period fall below the applicable AED 187,500 voluntary registration threshold, subject to the conditions in the VAT legislation.
The VAT Law distinguishes this from voluntary deregistration, which may be available where taxable supplies are below the AED 375,000 mandatory registration threshold. A person that registered voluntarily is also subject to restrictions on applying for deregistration during the first 12 months of registration.
Does Company Liquidation Automatically Cancel VAT Registration?
No. Company liquidation and VAT deregistration are related but separate processes.
A company can be involved in:
- Shareholder-approved liquidation;
- Appointment of a liquidator;
- Trade licence cancellation;
- Employee visa and labour file closure;
- Lease termination and utility disconnections;
- Corporate bank account closure; and
- Removal from the commercial register,
while still having an active VAT Tax Registration Number (TRN) with the FTA. A company should therefore track its commercial closure and tax closure separately. Allowing one process to finish does not automatically prove that the other has been completed.
Does Cancelling a UAE Trade Licence Automatically Cancel VAT?
No. Cancelling the trade licence does not automatically cancel the VAT registration. The company must separately apply through the FTA’s EmaraTax platform where VAT deregistration is required.
This distinction is particularly important for business owners who believe that receiving a trade licence cancellation certificate means every UAE government registration connected to the company has also ended. It may still be necessary to deal with:
- VAT deregistration and final VAT returns;
- Settlement of outstanding tax and administrative penalties;
- Corporate Tax deregistration and final tax period declarations;
- Immigration, establishment card, and customs clearances; and
- Other regulatory authority deregistrations.
VAT Deregistration During Company Liquidation: Documents the FTA May Require
The FTA’s current service information specifically identifies company-closure documentation where the business is no longer making taxable supplies because its licence has been cancelled. For a licence-cancellation case, relevant documents listed by the FTA include:
- Trade Licence Cancellation Certificate: Issued by the DED (Department of Economy and Tourism) or relevant Free Zone authority.
- Liquidation Letter / Report: Issued by the appointed legal liquidator confirming winding-up of affairs.
- Shareholder / Board Resolution: Documenting the official decision to dissolve and liquidate the entity.
A company’s liquidation file should be organized carefully so that the VAT application is consistent with the actual cessation date, licence status, accounting records, turnover figures, final transactions, and liquidation documentation.
UAE VAT Deregistration Process for a Closing Company (Step-by-Step)
Although individual cases differ, the VAT closure process can generally be approached in the following 9 stages:
Step 1: Determine the VAT Deregistration Trigger
Establish why the company is eligible or required to deregister. For a liquidating business, the trigger relates to the permanent cessation of taxable supplies. The relevant date must be established from actual business facts and supporting documentation rather than arbitrary dates.
Step 2: Review Outstanding VAT Returns
Before final deregistration is completed, review whether all VAT returns due up to that point have been properly submitted. Check sales reported, input tax claimed, reverse-charge transactions, imports, exports, and Free Zone transactions. Liquidation is not a reason to leave historic VAT errors unresolved.
Step 3: Review the Company’s Remaining Assets
This is one of the most frequently overlooked parts of VAT deregistration. The VAT Executive Regulation provides that goods and services forming part of the business assets may, in relevant circumstances, be treated as supplied immediately before deregistration (deemed supply), with any VAT due reflected in the final return. Review remaining inventory, machinery, equipment, vehicles, and furniture.
Step 4: Prepare the Closure Documentation
Collect licence cancellation documentation, liquidation letter, shareholder resolution, turnover declarations, final sales invoices, and asset disposal schedules. Information submitted to the FTA must reconcile with accounting and liquidation records.
Step 5: Submit the VAT Deregistration Application Through EmaraTax
Log in to EmaraTax → Select the taxable person account → Locate the VAT registration → Select Actions → Click De-Register → Complete the statutory declaration and upload supporting files. The FTA lists this service as free of charge.
Step 6: Respond to FTA Requests for Additional Information
The FTA may request turnover reconciliations or clarified cessation dates. Under current guidelines, the FTA may take up to 30 business days to review additional documentation once submitted.
Step 7: File the Final VAT Return
Submitting the deregistration application is not the end of the VAT process. The FTA states that the final VAT return and any payable tax must be submitted and settled no later than 28 days from the effective date of VAT deregistration.
Step 8: Settle Outstanding VAT and Administrative Penalties
The currently published VAT Executive Regulation states that a registrant will not be deregistered until due tax and administrative penalties are paid and required VAT returns have been filed.
Step 9: Obtain the Official VAT Deregistration Certificate
Once all liabilities, final returns, and penalties are cleared, a digital VAT Deregistration Certificate is generated through the EmaraTax dashboard. Retain this certificate in the company’s permanent corporate records.
What Is the Penalty for Late VAT Deregistration in the UAE?
Missing the applicable VAT deregistration deadline triggers administrative fines under Cabinet Decision No. 40 of 2017 (and subsequent amendments):
- AED 1,000 for late submission of the deregistration application;
- AED 1,000 on the same date monthly thereafter;
- AED 10,000 maximum cumulative penalty.
Waiting until after bank accounts are closed and finance staff have departed makes resolving these penalties significantly more difficult.
VAT Deregistration vs Corporate Tax Deregistration
VAT deregistration and Corporate Tax deregistration are two entirely separate FTA procedures governed by different laws and timelines:
| VAT Deregistration | Corporate Tax Deregistration |
|---|---|
| Governed by UAE VAT Decree-Law | Governed by UAE Corporate Tax Law |
| Requires separate VAT deregistration application | Requires separate Corporate Tax deregistration application |
| Final VAT return due within 28 days of deregistration | Final Corporate Tax return due for the cessation period |
| Distinct 30-business-day application window | Distinct timeline based on corporate cessation date |
| Issues digital VAT Deregistration Certificate | Issues Corporate Tax Deregistration Confirmation |
VAT Deregistration Considerations for Mainland, Free Zone & Inactive Companies
Whether your business is located in Dubai Mainland, an Abu Dhabi Free Zone, or has been dormant for years, tax compliance applies across all jurisdictions:
- Mainland Companies (Mainland Liquidation UAE): The liquidation must coordinate commercial licence cancellation with FTA VAT deregistration and Corporate Tax filings.
- Free Zone Entities (Free Zone Company Liquidation UAE): Free Zone or VAT Designated Zone status (such as JAFZA, DAFZA, DMCC, KIZAD, ADAFZ) does not exempt a VAT-registered business from mandatory deregistration upon closure.
- Dormant & Expired Companies: Allowing a commercial licence to lapse does not cancel the VAT TRN. Inactive companies continue to accrue filing obligations and potential penalties until formal FTA deregistration is completed.
Common VAT Deregistration Mistakes During Liquidation
- Waiting Until the Very End: Delaying tax deregistration until after all bank accounts and licences are cancelled.
- Assuming Licence Cancellation Cancels the TRN: These are completely separate government systems.
- Using the Wrong Deregistration Date: Declaring an arbitrary date rather than the actual cessation date supported by accounting records.
- Ignoring Deemed Supplies on Assets: Overlooking VAT implications on retained equipment, vehicles, or remaining inventory.
- Closing Bank Accounts Prematurely: Leaving the company unable to settle final VAT liabilities through EmaraTax.
Frequently Asked Questions About UAE VAT Deregistration in 2026
What is the UAE VAT deregistration deadline in 2026?
The FTA’s current VAT Deregistration service page, updated 24 September 2026, states that a mandatory deregistration application must be submitted within 30 business days from the date the deregistration obligation arose. However, because the published VAT Executive Regulation continues to state 20 business days, businesses should prepare and file promptly.
Did the UAE VAT deregistration deadline change from 20 to 30 business days?
The FTA’s live service page changed from 20 business days on its 10 September 2026 version to 30 business days on the version updated 24 September 2026. Businesses should distinguish the latest service guidance from the published regulatory wording.
Does company liquidation automatically cancel VAT registration?
No. A company registered for VAT must separately submit a deregistration application through EmaraTax when the applicable conditions arise.
Does cancelling the trade licence cancel the VAT TRN?
No. Trade licence cancellation and VAT deregistration are separate procedures administered by different authorities.
When must a company deregister for VAT?
Mandatory deregistration arises when the registrant permanently stops making taxable supplies or where its taxable supplies fall below the statutory AED 187,500 threshold over the relevant 12-month period.
Can a dormant company still be VAT registered?
Yes. Stopping business activity or allowing the commercial licence to expire does not automatically remove the company from the FTA VAT register.
What documents are required for VAT deregistration after company closure?
For licence-cancellation cases, the FTA requires a Trade Licence Cancellation Certificate, Liquidation Letter from the liquidator, Board Resolution, and relevant financial records.
How long does FTA VAT deregistration take?
The FTA’s current service page gives an estimated processing time of 30 business days from receipt of a completed application. If additional information is requested, a further period of up to 30 business days may apply.
When is the final VAT return due after deregistration?
The FTA requires the final VAT return to be submitted, and payable VAT settled, within 28 days from the effective date of deregistration.
Can the FTA reject or delay VAT deregistration if tax is outstanding?
Yes. Final approval is withheld until all due taxes, penalties, and outstanding returns up to the effective deregistration date are settled.
What is the penalty for late VAT deregistration?
AED 1,000 for late submission and AED 1,000 monthly thereafter, up to a maximum of AED 10,000.
Do Free Zone companies need VAT deregistration?
Yes. Free Zone status does not exempt a VAT-registered business from mandatory FTA deregistration when closing.
Is VAT deregistration the same as Corporate Tax deregistration?
No. They are separate FTA registrations with distinct legal frameworks, filings, and compliance deadlines.
Will I receive proof that the VAT registration has been cancelled?
Yes. Once approved and final obligations are settled, a digital VAT Deregistration Certificate is issued through EmaraTax.
Need Help Closing a VAT-Registered UAE Company?
If your company is undergoing liquidation, licence cancellation, or closing after inactivity, The Capital Zone Business Liquidators coordinates end-to-end commercial liquidation, VAT deregistration, Corporate Tax filings, and official authority clearances.

All Categories
Recent Posts
Corporate Tax Deregistration During UAE Company Liquidation: What Business Owners Need to Know
What Records Must You Keep After Closing a UAE Company? New FTA Record-Keeping Rules for 2026
Metal Scrap VAT During UAE Company Liquidation in 2026: What Businesses Need to Know
Quick support proccess
+971 50 209 9514